

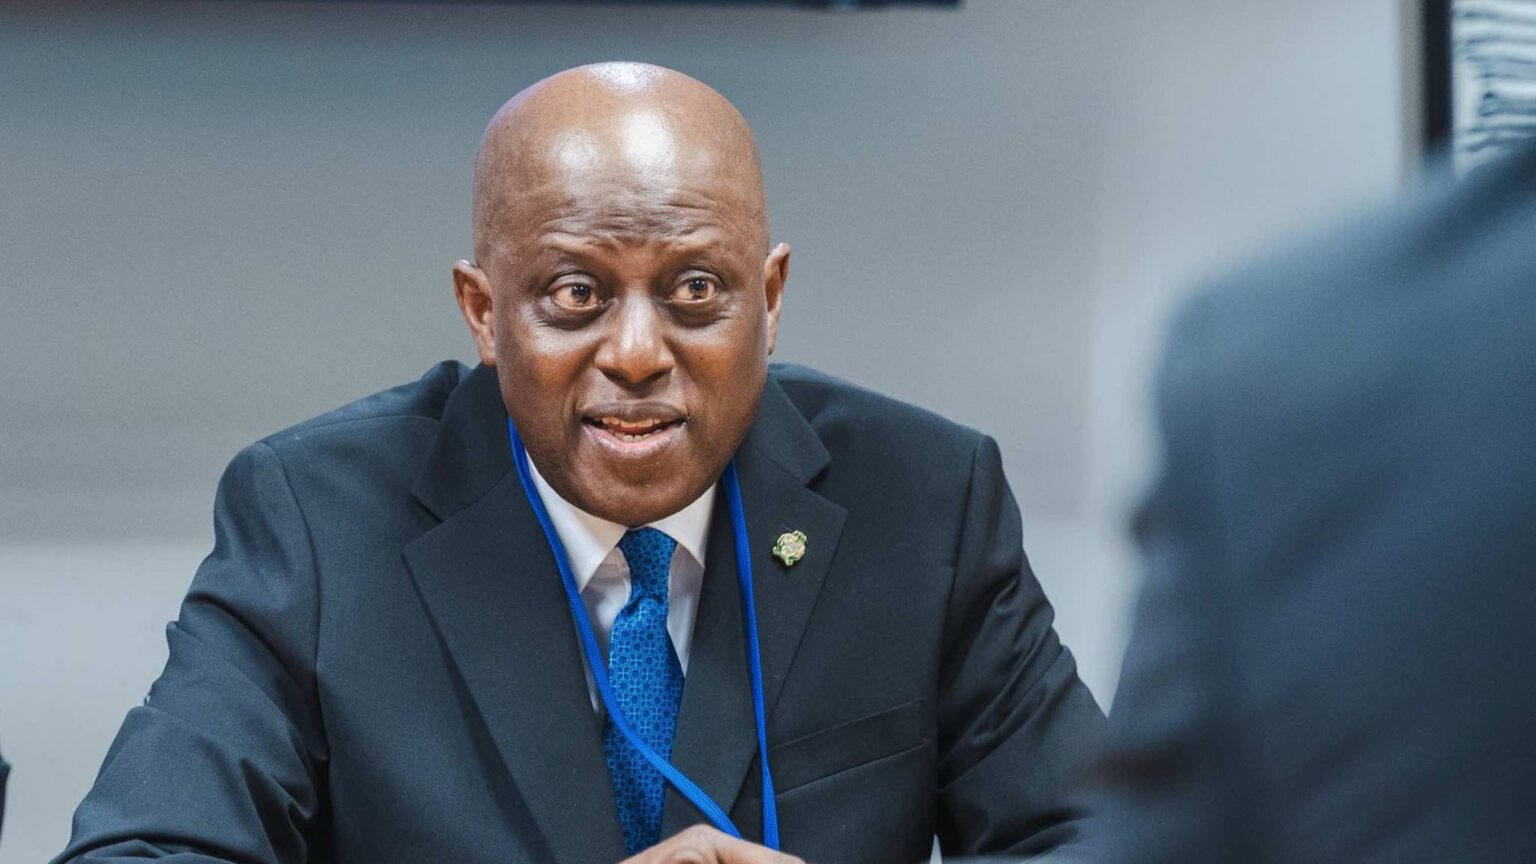
CBN Governor Olayemi Cardoso
- Slashes MPR by 3.5% amid global policy divergence
- Cheaper credit may fuel asset bubbles, higher inflation
- Cardoso defends reforms as reserves rise to $55.25b
The Monetary Policy Committee’s (MPC) decision to reduce the benchmark interest rate by 3.5 per cent to 23 per cent may provide much-needed relief to businesses and borrowers, but the unexpectedly steep cut increases foreign exchange (FX) risks, complicates the effect of rising political risks on capital inflows and could trigger asset price bubbles.
The decision, coming at a time when several major central banks are becoming dovish, could narrow Nigeria’s interest-rate advantage and test the resilience of recent gains in FX market stability.
This month, both the United States Federal Reserve and the European Central Bank (ECB) raised their anchor rates by 25 basis points amid renewed inflationary pressures triggered by the crisis in the global energy market.
For international investors, the implication of the policy divergence is that the price of money is falling in Nigeria while it is stable or rising elsewhere, suggesting that those who have invested have more reason to review their commitments.
A significant increase in capital outflows, a fall in inflows, or both, could increase pressure on naira stability. A demand-supply mismatch may call for more aggressive official intervention to keep the currency stable or a significant depreciation of the naira.
EFN Non Oil Export
The naira has been reasonably stable in the past two years. A pro-market reform executed by the interim management led by Folashodun Shonubi caused a sharp depreciation.
But the 2025/2026 improved performance moderated the post-liberalisation loss to about 65 per cent. The gain is now being tested, but with external reserves at an 18-year high of $55.25 billion and crude prices still trending upward, some analysts believe the country is in a comfort zone.
Announcing the MPC decisions after a two-day meeting yesterday in Abuja, CBN Governor Yemi Cardoso also announced a recalibration of the standing facilities corridor to +50/-300 basis points around the MPR.
This puts the transaction corridor at between 20 per cent and 22.5 per cent. It had risen to nearly 30 per cent at the height of the recent tightening.
The apex bank retained the cash reserve requirement at 45 per cent for deposit money banks, 16 per cent for merchant banks and 75 per cent for non-Treasury Single Account (TSA) public-sector deposits.
The combination of a substantially lower policy rate with unchanged reserve requirements suggests that the CBN is attempting to reduce the cost of credit without completely abandoning its control over system liquidity.
For businesses that have endured elevated financing costs during the CBN’s tightening cycle, the critical question is whether the reduction in the benchmark rate will translate into significantly cheaper commercial lending.
Cardoso described the move as an operational reset rather than a shift towards monetary easing.
Cardoso, who is also the Chairman of the Monetary Policy Committee (MPC), said the objective was to strengthen monetary-policy transmission and restore the MPR as the principal signal of monetary policy after the divergence between the policy rate and market rates had weakened transmission.
That distinction could prove particularly important for manufacturers, who see the cost of borrowing as only one component of a broader cost crisis involving energy, logistics, imported raw materials, FX challenges and multiple taxation.
CBN research had previously established a negative relationship between lending rates and manufacturing output, saying higher lending rates constrain manufacturing activity.
The implication is that if the latest rate reduction is effectively transmitted through the banking system, lower financing costs could improve manufacturers’ ability to fund working capital, acquire machinery, expand capacity and undertake longer-term investments.
However, the apex bank expressed concerns about the transmission challenge because the MPR is the CBN’s policy signal; it is not the rate at which most manufacturers borrow from commercial banks. The final cost of credit also reflects banks’ funding costs, risk assessments, operating expenses, capital requirements, collateral requirements and expectations about inflation and the exchange rate.
The steep rate cut could be seen as a generous third-anniversary gift to the ailing economy, coming exactly three years after Cardoso assumed office.
Cardoso also defended his performance, saying his team had moved the economy away from a period of severe monetary and foreign-exchange distortions.
He pointed to the restoration of the CBN’s core mandate, the removal of multiple exchange-rate distortions, the rebuilding of external reserves, banking-sector recapitalisation and increased diaspora remittances as major milestones of the administration.
Indeed, after three years dominated by monetary tightening, exchange-rate reform and efforts to rebuild confidence in the financial system, the apex bank is now attempting to determine whether the stability it says it has restored is sufficiently durable to permit lower policy rates without reversing the gains made against inflation.
Cardoso said the starting point for his administration was an economy in which confidence in the currency and the central bank had deteriorated sharply.
He recalled a period of rapid naira depreciation, multiple exchange rates and widespread uncertainty over prices, saying the instability encouraged people to move their savings into foreign currency and contributed to a loss of confidence in the domestic financial system.
He also pointed to the scale of the CBN’s Ways and Means exposure at the time, putting it at about N23.7 trillion, alongside more than N10 trillion in interventions.
According to him, the accumulation of liquidity through these channels contributed to the inflationary pressures confronting the economy.
The subsequent policy response, he said, was to return the central bank to its statutory mandate of maintaining price and financial stability.
One of the most consequential reforms was the restructuring of the foreign-exchange market.
Cardoso argued that the former multiple-rate regime created substantial distortions because access to foreign currency depended on the window available to an individual or business.
He revealed that gross external reserves stood at $55.25 billion on September 18, 2026, representing the highest level in 18 years and equivalent to about 11.3 months of import cover.
The governor attributed the improvement to consistency and discipline in policy, while also drawing particular attention to diaspora remittances.
He said remittances had become an important source of resilience and had helped build Nigeria’s external buffers.
The MPC reported a balance-of-payments surplus of $3.51 billion in the second quarter of 2026, compared with $2.38 billion in the first quarter, while the current-account surplus increased by 67.92 per cent to $7.54 billion from $4.49 billion.
The improvement has provided an important cushion for the latest monetary-policy reset.
Reacting to the decisions, the Centre for the Promotion of Private Enterprise (CPPE) described the rate cut as a timely and significant shift away from the restrictive policy stance the CBN had maintained since late 2023.
In a policy brief, the CPPE Chief Executive Officer, Dr Muda Yusuf, said the size of the cut was largely unexpected and signalled a rebalancing of monetary policy towards growth, investment and economic recovery, while still preserving price and financial stability.
Yusuf noted that a widening gap had existed between the old MPR of 26.5 per cent, inflation of about 15.4 per cent and money-market rates of around 20 per cent, a mismatch that weakened the signalling power of the policy rate. He described the new rate as a realignment of monetary policy with actual market conditions rather than mere easing.
He said the decision would offer major relief to the real sector, particularly manufacturing, agriculture, construction and logistics, where high financing costs have constrained investment and job creation. He, however, cautioned that the benefits would depend on banks passing on lower rates to borrowers.
The CPPE also pointed to positive implications for government finances, noting that a sustained drop in interest rates should reduce the cost of government borrowing and create more fiscal space for infrastructure and other priorities.
It warned, though, that the rate cut carries exchange-rate and portfolio-flow risks, given diverging monetary policy trends between Nigeria and some major economies, although improved reserves give the CBN more room to manage these risks.
The CPPE said the success of the policy would ultimately be judged by falling lending rates, credit growth to productive sectors, inflation behaviour and exchange-rate stability.
Chief Investment Officer at VNL Capital Asset Management, Dr Ifeanyi Ubah, described the cut as a strong signal that the CBN was reading Nigeria’s inflation trajectory, naira stability and reserve position with more confidence than the market had priced in. He said retaining the CRR showed that the Committee was easing the cost of credit without loosening overall liquidity control.
A financial analyst, Abiodun Ogunniyi, said the cut would likely trigger a rotation of capital from fixed income into equities, as yields fall and bond prices rise. He named consumer goods, industrial goods and oil and gas as sectors likely to benefit from cheaper capital, describing the effect on banks as mixed, given the trade-off between loan growth and reduced interest income.
The Guardian


